FinCEN withdraws $10,000 reporting rule for crypto transfers to private wallets
The Financial Crimes Enforcement Network (FinCEN) has officially scrapped its proposed rule that would have mandated reporting of cryptocurrency transactions exceeding $10,000 when sent to private wallets. This move comes after years of uncertainty surrounding the regulation, which had raised concerns among crypto users and industry stakeholders alike. The rule had been under discussion since late 2020 but never came into effect, leaving many in the crypto community in limbo regarding compliance requirements and the implications for self-custody wallets and crypto mixers.
The context of this decision is rooted in the increasing scrutiny of cryptocurrency transactions by regulatory bodies in the United States. The initial proposal aimed to enhance transparency and combat money laundering by requiring financial institutions to report large transactions. However, critics argued that such regulations would disproportionately affect individual users who prefer to self-custody their assets, potentially stifling innovation and driving users away from the regulated financial system.
This withdrawal is significant for the crypto market as it alleviates some regulatory pressures that have been looming over self-custody solutions. By not imposing reporting requirements on private wallets, the decision is likely to encourage more users to hold their assets independently, further promoting the adoption of decentralized finance (DeFi) and self-custody practices. It may also provide a more favorable environment for crypto mixers, which have faced heightened scrutiny due to their association with anonymity in transactions.
Industry experts have reacted positively to this news, viewing it as a win for individual privacy and personal control over assets. Many in the community believe that this decision reflects a growing recognition by regulators of the unique characteristics of cryptocurrency and the need for a balanced approach to regulation that protects users without stifling innovation. Some advocates hope that this will lead to a more collaborative dialogue between regulators and the crypto community to establish a framework that supports growth while addressing legitimate concerns about illicit activities.
Looking ahead, the crypto industry is keenly watching how this decision may influence future regulatory proposals. With the withdrawal of the reporting rule, it could signal a shift toward more user-friendly regulations that prioritize innovation and user autonomy. Stakeholders will likely advocate for clearer guidelines that promote transparency without compromising the decentralized ethos of the cryptocurrency ecosystem.

CoinMagnetic Team
Crypto investors since 2017. We trade with our own money and test every exchange ourselves.
Updated: October 2026
From our insights:
Related news
Ethereum validator client updates software ahead of major Sepolia test
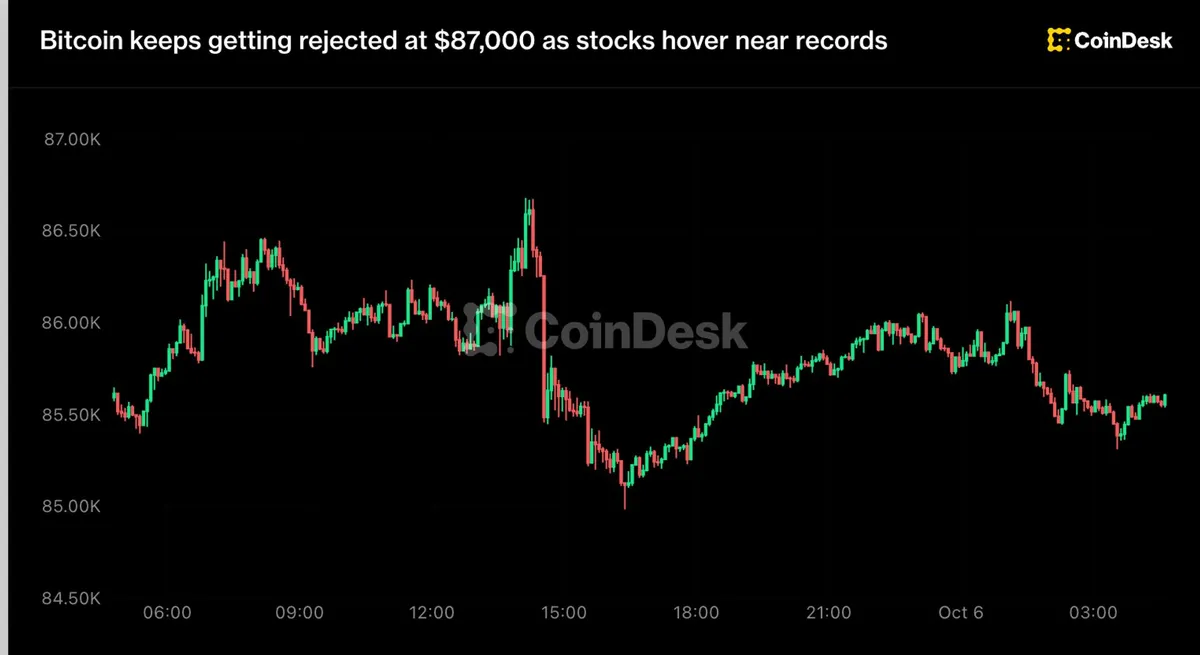
Bitcoin faces third rejection at $87,000 as stocks reach new highs
Strive's $169 million bitcoin acquisition marks largest purchase in four months
Anthropic's safety filters trigger police report from woman's Claude diary
4chan user predicts end of crypto winter aligns with Bitcoin's October peak